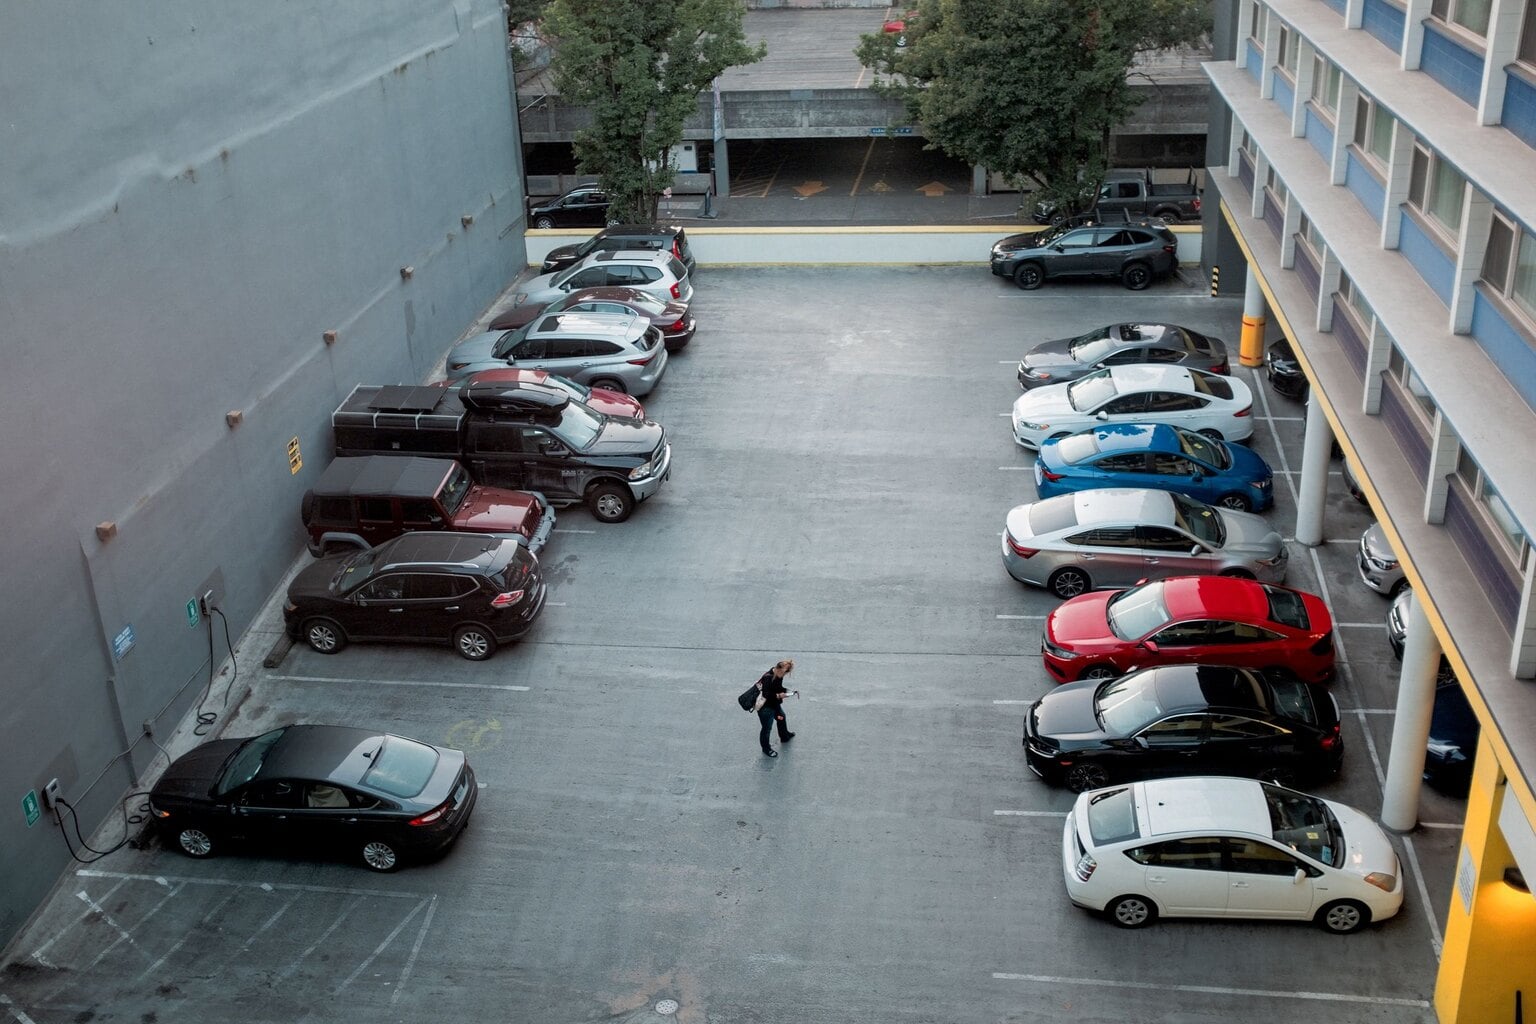
Plenty of people drive their own car for work without ever registering a business vehicle. A sales rep doing client visits, a nurse driving between patient homes, a freelancer collecting supplies. All of them are running up personal car business mileage, whether they are recording it or not.
How that mileage turns into money depends on one thing above all others: whether you are self-employed or on someone’s payroll. The rules are different, the paperwork is different, and mixing them up is the most expensive mistake in this whole subject.
Key takeaways
- Self-employed drivers deduct. Employees claim reimbursement. Those are different processes with different paperwork.
- Your business-use percentage is business miles over total miles — and it has to trace back to a log, not an estimate.
- Most personal auto policies exclude business use by default, which is the gap drivers discover after an accident rather than before.
- Employers with staff driving personal cars often carry their own non-owned auto cover. It protects the company, not your car.
- Two vehicles means two sets of records. Note which car made each trip.
Two Ways People Use a Personal Car for Work
If you are self-employed, your personal car business mileage goes on Schedule C. You choose between the standard mileage rate and the actual expense method, and the deduction reduces your own taxable income. There is no employer in the picture. The filing side of that — rates, method choice, what to keep and for how long — is covered in how to track mileage for taxes.
If you are an employee, the route is reimbursement rather than deduction. Most employees can no longer deduct unreimbursed business mileage at all — that deduction was suspended in 2018 and has since been made permanent, with only narrow exceptions such as Armed Forces reservists, qualified performing artists and fee-basis state or local officials. In practice this means an employee with no reimbursement policy has no tax route either, which is worth knowing before you spend a year logging trips in hope.
| Situation | How the mileage is handled | Who gains |
|---|---|---|
| Self-employed | Deducted on Schedule C | You, through a lower tax bill |
| Employee, accountable plan | Reimbursed by the employer, not taxed as wages | You, through direct payment |
| Employee, no reimbursement policy | Generally neither deductible nor reimbursed | Nobody, until the policy changes |
Some employers also expect you to carry related costs — parking through Way, tolls — out of pocket, or reimburse them separately from the per-mile rate. Worth establishing which, in writing, before you assume.
Working Out Your Business-Use Percentage
Almost nobody using a personal car for work drives it exclusively for work. A freelancer might do client visits three days a week and the school run on the other four. What matters is not your total driving but the share of it that is genuinely work-related.
The arithmetic is simple: business miles divided by total miles for the same period. Drive 12,000 miles with 4,000 documented business trips and your business use is about 33%.
Two things make that number more than a curiosity. If you use the actual expense method, it is the multiplier applied to your whole running cost — insurance, repairs, depreciation — so a few points either way is real money. And it is the figure most likely to be questioned, because a vague estimate is easy to spot: it tends to be round, and it tends to be the same every year. Reviewers expect it to trace back to a log.
What Counts, Whichever Side You Are On
The definition of a business trip does not change with your employment status, even though how you claim it does.
Generally qualifies:
- Client meetings, job sites, work appointments.
- Errands that serve the business directly, such as collecting supplies.
- Travel between two work locations in one day.
- Trips to a temporary work location off your usual route.
Generally does not:
- The regular commute between home and your main workplace.
- Personal errands, even during working hours.
- The purely personal leg of a mixed trip.
Fuel follows the same logic. A fill-up for a business trip, whether or not you found it through Way Gas, belongs to that trip rather than to your general motoring. The awkward middle cases — mixed trips, working from home, two jobs in one car — are covered in business vs personal mileage.
Tracking It, Step by Step
1. Settle the method or the policy first. Self-employed drivers should choose standard rate or actual expenses early, since the first year’s choice affects later switching. Employees should get the reimbursement policy in writing.
2. Log each trip the day it happens. A few days is enough for a stop to go missing or a purpose to blur.
3. Name the purpose specifically. “Client visit” passes; naming the client or project is what gives the entry weight if anyone asks.
4. Separate business and personal immediately. Tag as you go rather than sorting a week of mixed driving from memory.
5. Record the odometer at both ends of the year. These anchor your total and support the percentage you claim.
6. File or submit on a schedule. Employees to their employer’s deadline; self-employed drivers by keeping records current rather than rebuilding a year each spring.
The Insurance Gap Most Drivers Never Check
This is where the two situations split in a way that catches people out, and it is the part of this subject with the worst downside.
Most personal auto policies exclude business use by default. If you are self-employed, that gap is yours to close — usually by disclosing the business use to your insurer, who may add a rider or move you to a commercial policy depending on how much you drive for work.
If you are an employee, your employer may carry hired and non-owned auto insurance, which covers the company’s liability when a member of staff causes an accident on a work trip. The thing to understand is what it is not: it protects the employer, not your vehicle, and it does not replace your own policy. It closes a gap for the business rather than for you.
| Situation | Who typically carries business-use liability |
|---|---|
| Self-employed | Your own policy, once the business use is disclosed |
| Employee, employer holds non-owned auto cover | The employer’s policy, for the company’s exposure |
| Employee, no employer cover | Potentially a gap — worth raising with HR |
None of this is legal or insurance advice, and policy wording varies more than any summary can capture. The useful action is small: one call to your insurer describing how you actually use the car, and one question to HR about what the company carries. Both are cheap now and expensive to have skipped.
Records That Hold Up
Whichever side you are on, the IRS and most finance teams want the same four things on every trip:
- The date.
- Start point and destination.
- A specific business purpose.
- Miles driven.
Self-employed drivers should keep these at least three years past filing, and six where income might have been significantly understated. Employees mainly need to meet the employer’s submission window, but keeping your own copy costs nothing and settles disputes. For the full field-by-field version, see how to keep an IRS mileage log.
Common Mistakes
- Assuming the employer has you covered. Not every company carries non-owned auto cover, and the ones that do are covering themselves. Ask rather than assume.
- Mixing employee and self-employed rules. Freelancing alongside a job means two separate logs, not one.
- Rebuilding trips from memory. A log written weeks later rarely matches what happened.
- Forgetting EV charging. Charging for work trips counts the same as fuel, including short top-ups at a nearby EV charger — easy to miss precisely because it happens in small sessions rather than one obvious stop.
- Letting odometer readings lapse. Without both ends of the year, your total has no anchor and your percentage has nothing behind it.
- One log for two cars. Mileage is tracked per vehicle. If you switch, the log should say which car drove the trip.
Keeping It Straight Without the Admin
The more one car does both jobs, the harder this is to hold together by hand. The Way mileage tracker logs trips by GPS and sorts business from personal with a single tap:
- Automatic logging, with no trip to remember to start.
- One-tap sorting, close enough to the drive that you still know why you made it.
- Exportable reports for an employer or an accountant.
- Support for several vehicles, if work and personal driving happen in different cars.
- A running record to check a total or a percentage against.
Where a business has several people driving their own cars, Way’s mileage tracker for teams collects every trip in one dashboard, which turns reimbursement from a monthly chase into a report.
A running record also makes the wider picture visible — how work driving sits inside the total cost of keeping the car on the road. Way’s guide to the average cost of owning a car is a useful companion to that.
Frequently Asked Questions
Can I deduct mileage my employer already reimburses?
No, not for the reimbursed portion under an accountable plan. And most employees cannot deduct unreimbursed business mileage either, which leaves reimbursement as the practical route.
Do I need special insurance to use my own car for a side business?
Possibly. Occasional use rarely causes a problem; regular business driving often does. Describe your actual usage to your insurer and ask whether a rider or commercial policy applies — more so if you carry tools, equipment or passengers for the job.
What if I drive for a full-time job and a freelance gig?
Keep completely separate logs. A combined record makes it much harder to substantiate either the reimbursement claim or the deduction later.
Is it different for gig economy drivers?
Gig drivers are generally self-employed for tax purposes even though a platform assigns the work, so most miles driven while active count as business. The drive from home to a first pickup is a grey area worth checking with a tax professional.
Does it matter which car I use if I own two?
Yes. Mileage and expenses are tracked per vehicle, so the log should record which car made each trip.
What if my employer does not reimburse mileage at all?
Ask about the policy first, since reimbursement is not federally required in most states — California, Illinois and Massachusetts are the notable exceptions. If none is offered, a W-2 employee generally cannot deduct the mileage instead.
I changed from employee to self-employed mid-year. One log or two?
Two. Keep the periods separate, because different rules apply to each stretch of the year and a merged log makes both harder to substantiate.
How exact does my business-use percentage need to be?
Exact enough to trace to your log. It is a calculation from recorded miles rather than a figure you choose, and a suspiciously round number that repeats year to year is the kind of thing that attracts a question.
Where This Leaves You
Tracking personal car business mileage gets much easier once you know which set of rules applies to you. Self-employed means a deduction and a method choice; employed means a reimbursement claim and an employer policy. Almost every avoidable mistake here comes from applying one situation’s rules to the other.
After that it is routine: keep business and personal apart, record the detail while it is fresh, note the odometer at both ends of the year, and make sure your insurance matches how you actually use the car. The last of those is the one people skip, and the only one with a five-figure downside.
Get 10% off in the Way App in the Way App!
- Scan and get the Way App Download the Way App
- Log in to your account
- Use code FIRST10 at checkout